
In brief
A recently published decision of the Hessian Tax Court could significantly narrow how far the German Royalty Barrier Rule (RBR) in Section 4j of the German Income Tax Act (Einkommensteuergesetz, (EStG)) may reach. Although the RBR has since been repealed and no longer applies after 2024, the judgment could still have significant implications for taxpayers with open assessment periods from 2018 through 2024. This applies in particular to multinational groups whose German subsidiaries paid royalties to related parties benefiting from preferential regimes not specifically targeted at royalty income, such as the former Swiss cantonal holding, domiciliary or mixed company regimes.
In more detail
Executive summary
The Hessian Tax Court’s judgment of 4 November 2025 (8 K 1324/22), released on 29 June 2026, significantly narrows the scope of Germany’s RBR. The court held that the RBR applies only to preferential regimes that expressly and exclusively target income from the licensing of rights (such as IP, patent or license boxes). It rejected the tax authorities’ view that it suffices for a regime to also cover royalty income, for example a regime that applies a reduced rate to all foreign-source income.
The decision may provide relief for taxpayers that paid royalties to related parties benefiting from non-IP-specific preferential regimes in the assessment periods 2018 through 2024, including certain former Swiss cantonal regimes and potentially comparable regimes in other jurisdictions. Although the judgment is currently under appeal before the Federal Tax Court (I R 29/25), affected taxpayers should consider invoking the decision in ongoing tax audits. They should also preserve their rights through timely objections and procedural safeguards where appropriate.
Discussion
Germany introduced the RBR in 2017 with effect as from 2018 in response to BEPS Action 5. The goal was to stop profits being shifted to IP, license and patent boxes that do not require substantial activity (Modified Organisation for Economic Co operation and Development (OECD) Nexus Approach).
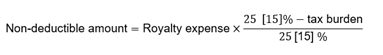
The rule concerned the deductibility of royalty expenses paid directly or indirectly to a related party. Such royalty expenses were fully or partly non-deductible if the recipient’s income was subject to a low-tax preferential regime that deviated from regular taxation. “Low tax” initially meant below 25%. The threshold was later reduced to 15% as from 1 January 2024. The RBR applied regardless of any double tax treaty. Regimes that complied with the Modified OECD Nexus Approach were carved out. The non-deductible portion was generally calculated as follows:
The German tax authorities have read “preferential regime” broadly (Federal Ministry of Finance, Circulars of 19 February 2020, 5 January 2022 and 6 January 2022). In their view, any regime counts, whether tied to the type of income, legal form, place of management or seat, as long as it also covers royalty income. According to the authorities, even individual tax rulings agreed between foreign tax authorities and royalty recipients can qualify as a preferential regime.
The decision of the Hessian Tax Court concerned the 2018 assessment period. In that case, a German company paid royalties to the Swiss branch of a related Cypriot company. That branch was taxed under the Swiss cantonal mixed company regime, which taxed all foreign income at a reduced rate, regardless of its type. The tax office applied the RBR and allowed only part of the royalty expense as a deduction.
The court ruled in favor of the taxpayer. It accepted that the mixed company regime deviates from regular taxation, as it was designed to attract mobile activities to Switzerland. However, the court held that the requirement of a deviation from regular taxation must be interpreted narrowly. According to the court’s view, it covers only regimes that expressly and exclusively target income from the licensing of rights, and not regimes that, like the mixed company regime, grant a reduced rate to all foreign income regardless of its type.
The court advanced three principal arguments in support of its narrow interpretation:
- Statutory wording. According to the court, the reference to the “income of the creditor” in Section 4j(1) EStG must be interpreted in conjunction with the reference to “income from the licensing of rights” in Section 4j(2) EStG. In the court’s view, the RBR requires a direct link between the non-deductible royalty expense in Germany and a preferential tax treatment specifically granted to the corresponding royalty income at the level of the recipient.
- Legislative history and purpose. The explanatory memorandum consistently refers to IP, license and patent box regimes and expressly links the scope and purpose of Section 4j EStG to the OECD BEPS Action 5 project. In the court’s view, this demonstrates that the provision was intended to address preferential regimes targeting income from the exploitation of IP rather than low-tax regimes more generally.
- The nexus-based exception. The exemption for preferential tax regimes that comply with the Modified OECD Nexus Approach applies exclusively to preferential regimes specifically targeting income from IP exploitation. The court inferred from this that the core rule in Section 4j(1) EStG must likewise be limited to such IP-specific regimes. In the court’s view, the exception would otherwise make little sense, as it would carve out only a narrow subset of regimes from a rule intended to capture all forms of preferential taxation, including those unrelated to IP income.
The case is currently pending before the Federal Tax Court (case no. I R 29/25). Whether the Federal Tax Court will uphold the decision of the Hessian Tax Court remains to be seen. It is noteworthy that the Hessian Tax Court’s decision has attracted criticism even from within the judiciary itself. In a commentary on the Hessian Tax Court decision, a tax judge at the Tax Court of Berlin-Brandenburg described the Hessian Tax Court’s reasoning as unpersuasive. In his view, the decisive question is whether the regime in question effectively also provides preferential treatment for royalty income, rather than how broadly or narrowly the regime is designed. The issue therefore remains controversial, with legal opinion divided, including among members of the tax judiciary.
Why this matters and which clients may be affected?
The decision is especially relevant for German taxpayers that paid royalties to related parties in the assessment periods 2018 through 2024 where the recipient benefited from a preferential regime not specifically targeted at royalty income. This includes, in particular, recipients subject to the former Swiss cantonal holding, domiciliary or mixed company regimes, which were abolished with effect from 1 January 2020 and are therefore relevant for 2018 and 2019. It is unclear whether the transitional rules introduced when these regimes were abolished also constitute preferential regimes for purposes of the RBR. If they do, the decision could also be relevant for later assessment periods up to and including 2024.
In addition, the court’s reasoning may also extend to other preferential regimes that grant preferential tax treatment based on factors such as legal form, status, location, or the source of income, rather than specifically targeting royalty income. The guidance issued by the Federal Ministry of Finance dated 6 January 2022 (BStBl. I 2022, p. 103), which lists preferential regimes that did not comply with the Nexus approach in the assessment periods 2018 through 2020, includes, in addition to traditional IP and patent box regimes, a significant number of regimes that did not specifically target royalty income, in particular:
- Special economic, free trade, and technology zones, e.g., the Aruba Free Zone, development zones in Jordan, special economic zones in Kazakhstan and free zones in Qatar, free trade zones in Mongolia and Uruguay, the Seychelles International Trade Zone, and Panama’s City of Knowledge technical zone;
- Offshore and international company regimes, e.g., international business companies in Barbados, Belize, Dominica, the Seychelles, St. Lucia, and St. Vincent and the Grenadines, Curaçao tax-exempt and export facility companies, offshore companies in St. Kitts and Nevis, Macau offshore institutions, and Mauritius Global Business Licence I and II companies; and
- Status- and sector-based incentive regimes, e.g., Malaysia’s MSC, BioNexus, Pioneer, and Principal Hub regimes, Singapore’s Pioneer and DEI-S incentives, and San Marino’s new companies regime.
Although most of these regimes have since been abolished, generally with effect from 2019 to 2021 at the latest, the court’s decision may remain relevant for the assessment periods in which these regimes still applied, since it can be argued, based on the court’s reasoning, that they fall outside the scope of the RBR.
The Hessian Tax Court’s decision does not address the Foreign-Derived Intangible Income (FDII). Nevertheless, its reasoning may be relevant. Despite its name, FDII is not limited to income from the licensing of rights. Under the standard applied by the Hessian Tax Court, which covers only regimes that expressly and exclusively target income from the licensing of rights, FDII falls outside the scope of the RBR. Accordingly, if the Federal Tax Court were to uphold the ruling of the Hessian Tax Court, this would also indirectly confirm, to the benefit of taxpayers who made payments to related parties that benefited from the FDII regime, that the RBR does not apply to them.
Conversely, even if the Federal Tax Court were to reject the Hessian Tax Court’s narrow interpretation and hold that the RBR also applies to preferential regimes not specifically targeted at royalty income, this would still not necessarily mean that FDII falls within the scope of the RBR. FDII differs from the former Swiss cantonal regimes in a number of relevant respects. The application of the RBR to FDII would therefore still require a separate assessment of whether FDII satisfies the statutory requirements of Section 4j EStG.
What should taxpayers do?
Taxpayers facing a potential royalty barrier adjustment in the course of a tax audit based on a non-IP-specific preferential regime should challenge the tax authorities’ position and refer to the Hessian Tax Court’s decision. They may argue that the royalty barrier rule does not apply where the preferential regime is not specifically targeted at IP income. If the tax authorities nevertheless make an adjustment, taxpayers should file an objection against the relevant assessment and expressly refer to the legal issue currently pending before the German Federal Tax Court (case no. I R 29/25). In that case, the objection proceedings should be stayed pursuant to Section 363(2), sentence 2 of the German Fiscal Code until the Federal Tax Court has issued its decision. Taxpayers wishing to defer payment of the additional tax pending the outcome of the proceedings should separately consider applying for a stay of execution.